Barndominium insurance is property coverage designed around a home that combines metal barn-style construction with residential living space. Because a barndominium may have a nontraditional frame, metal exterior, large open footprint, attached shop, or rural location, some major national carriers may decline it or classify it incorrectly under a standard homeowners policy. Herring Agency of Amarillo helps homeowners and prospective buyers in Amarillo TX and across Texas evaluate options for properly structured barndominium coverage.
What Is a Barndominium?
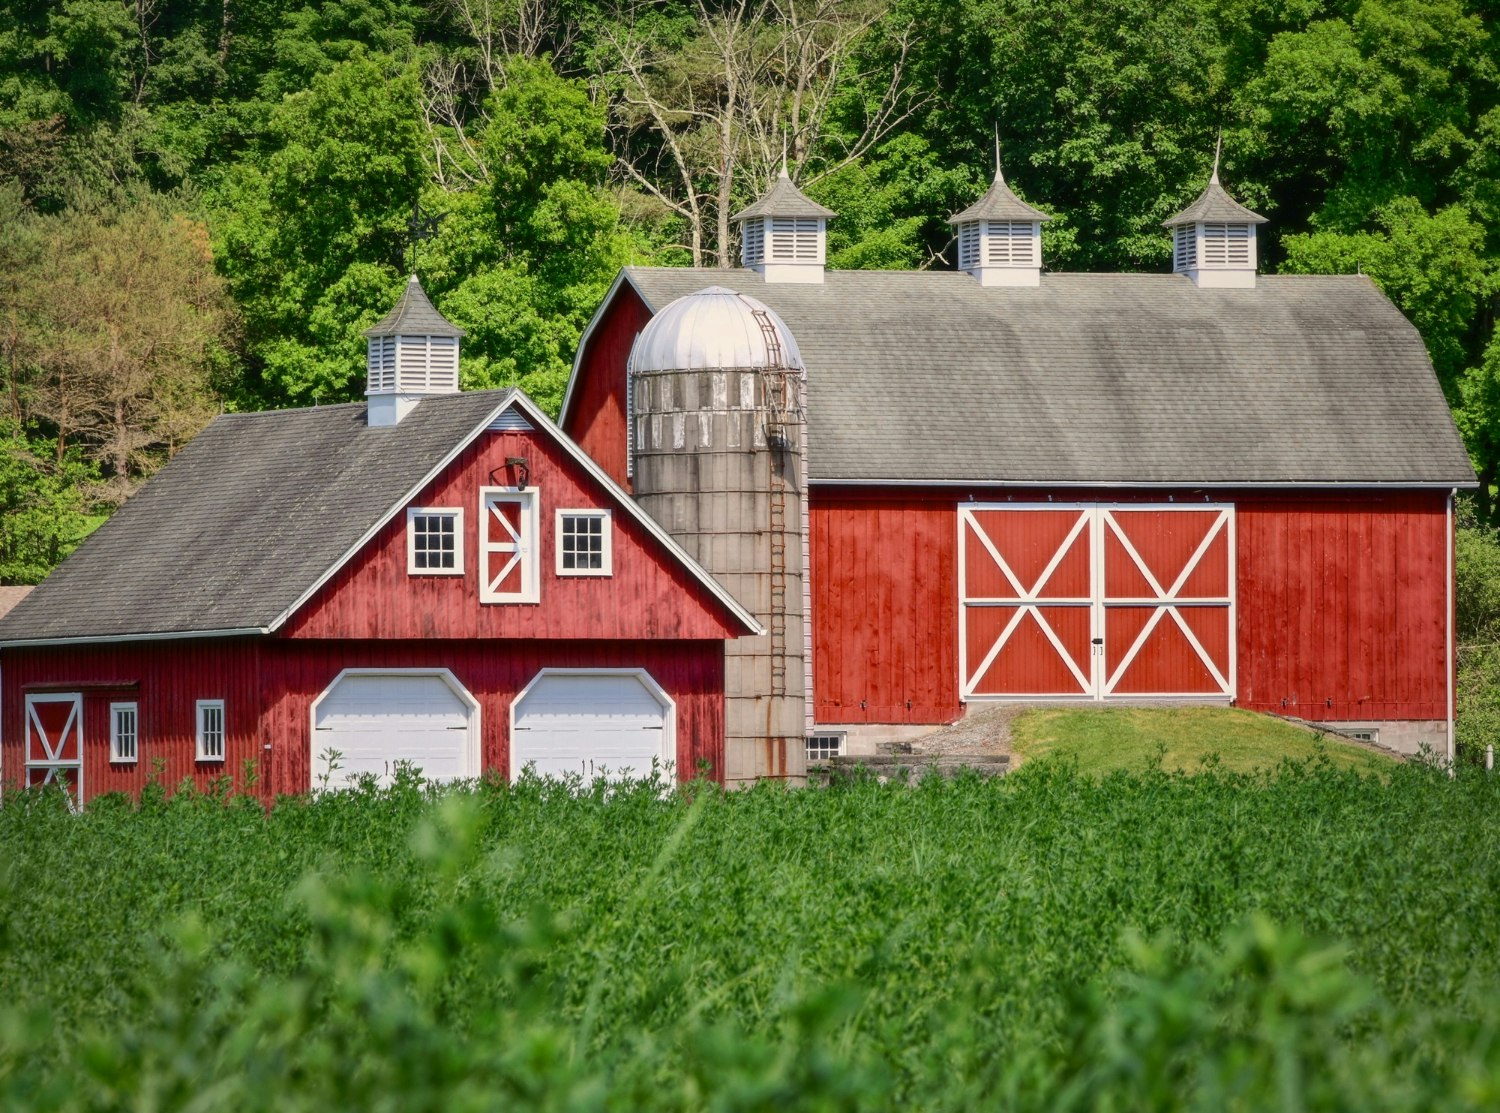
A barndominium—often called a “barndo”—is a residential home built in or modeled after a barn-style structure. Many feature metal-frame construction, metal siding or roofing, wide-span interiors, and a combination of living space with a garage, storage area, workshop, or agricultural-use area.
That flexibility is a major attraction for Texas property owners. But it also means an insurer needs an accurate picture of how the building is constructed and used. A barndominium that is solely a primary residence can be evaluated very differently from one that includes a business workshop, farm equipment, livestock operations, rental activity, or extensive storage.
Why Standard Homeowners Coverage May Not Fit
A conventional homeowners policy is generally designed for a traditionally built residence. When a barndominium is entered into a carrier’s system as an ordinary house—or, on the other end of the spectrum, as an outbuilding—the valuation and coverage approach may not reflect the property you actually own.
Common underwriting questions include the percentage of the building used as living space, the type of foundation and frame, the age and condition of the structure, the roof material, its distance from a fire department, and whether the site is rural. A policy that overlooks the attached shop or understates the cost to rebuild a metal-frame home can leave unwelcome gaps after a covered loss.
Before buying or building, ask for a policy review that identifies the home’s full square footage, construction details, occupancy, attached structures, and intended uses. Herring Agency of Amarillo can help make sure those details are presented clearly when seeking Barndominium Insurance.
How an Independent Agency Helps Find Coverage
Not every insurer writes every kind of barndominium in Texas. An independent agency can compare available carrier options rather than relying on a single company’s underwriting rules. That matters when one carrier is comfortable with a metal home used strictly as a residence while another is better suited to a rural property with additional structures or farm exposures.
The goal is not simply to find a policy that can be issued. It is to find coverage that accurately matches the structure, rebuild estimate, deductible, roof settlement terms, personal-property needs, and liability exposure. Herring Agency of Amarillo works with homeowners statewide, including clients in Amarillo TX, to review those details before coverage is bound.
The Four Core Parts of Barndo Insurance
Although policy forms and limits vary by carrier, a well-designed barndo insurance plan commonly addresses four essential categories:
- Dwelling coverage: Helps pay to repair or rebuild the insured residence after a covered loss. The dwelling limit should be based on a realistic reconstruction cost—not the land value, tax appraisal, or purchase price alone.
- Personal property coverage: Helps protect belongings inside the living area, such as furniture, clothing, electronics, and appliances. Tools, equipment, collectibles, and property kept in a shop may have separate limits or coverage requirements.
- Personal liability coverage: Helps protect you if you are legally responsible for injury to someone else or damage to another person’s property. Consider the liability implications of visitors, recreational features, animals, or regular activity on the property.
- Additional living expenses: May help with certain necessary increases in living costs when a covered loss makes the residence uninhabitable. This can be especially important when the property is in a rural Texas location with limited temporary-housing choices.
Replacement Cost vs. Actual Cash Value for Metal Homes
One of the most important questions in insurance for metal homes is how a claim is settled. Replacement cost
is designed to reflect the cost to repair or replace covered property with materials of like kind and quality, subject to the policy’s terms and limits. Actual cash value
generally accounts for depreciation, which can reduce the amount paid for an older roof, building component, or personal item.
For a metal-frame barndominium, confirm how the dwelling, roof, and attached areas are valued. Metal materials may be durable, but they are not automatically inexpensive to repair or replace, particularly when labor, specialized components, insulation, finishes, electrical systems, and custom interior build-outs are considered. Ask whether the policy provides replacement cost for the dwelling and whether any roof or component limitations apply.
When Your Barndominium Includes a Shop or Agricultural Area
An attached shop is not always treated the same as the home’s living area. If it is used only for personal hobbies or household storage, it may be considered as part of the dwelling or another covered structure, depending on the policy. If it is used for a business, customer visits, paid repair work, manufacturing, inventory, or commercial equipment, a homeowners policy may not fully cover those exposures.
The same principle applies to working agricultural areas. Farm tools, tractors, livestock, hay, outbuildings, and farm-related liability may require separate farm, ranch, or equipment coverage. Do not assume that a policy covering the residence automatically covers every use of the land or every item inside the shop. Be upfront with your agent about how the space is used so the policy can be built around the real risk.
Questions to Ask Before You Build or Buy
- Will the carrier insure the structure as a primary residence, secondary home, or rental?
- What dwelling limit is needed to rebuild the completed barndominium?
- Is the roof settled on replacement cost or actual cash value?
- How are the attached garage, shop, and non-living portions of the structure covered?
- Are business, agricultural, rental, or equipment exposures excluded or limited?
- What wind, hail, and other deductibles would apply in your part of Texas?
A review before construction is complete can make the quoting process smoother and help prevent an unpleasant surprise at closing. Herring Agency of Amarillo can coordinate the conversation around the construction plans, property use, and coverage priorities that matter most to you.
FAQ
Does Germania Insurance cover barndominiums?
Germania Insurance offers rural property insurance in Texas and identifies barndominiums among the types of properties it can help protect. Eligibility, available coverages, limits, deductibles, and underwriting requirements depend on the specific property and how it is used. Herring Agency of Amarillo can help you determine whether a Germania Insurance option fits your barndominium.
What carriers will insure a barndominium in Texas?
The available carriers depend on the barndominium’s construction, location, occupancy, roof, square footage, attached spaces, and business or agricultural use. Rather than relying on a generic list, work with an independent agent who can assess the details and shop appropriate options for your Texas property.
What if my barndominium has a workshop?
Tell your agent exactly how the workshop is used. A personal hobby space may be handled differently from a business workshop or an area storing expensive tools, farm equipment, or inventory. You may need additional coverage, endorsements, or a separate policy to protect the space and its liability exposure properly.
Can I insure a barndominium before construction is finished?
In many situations, you can begin discussing coverage before completion. Early planning gives you time to document construction specifications, estimate rebuilding costs, identify the intended use of each area, and understand what coverage will be needed when the home is ready for occupancy.
Get a Barndominium Insurance Quote in Texas
Whether you are planning a new build, buying an existing barndo, or reviewing current coverage, Herring Agency of Amarillo can help you evaluate options for your Texas property. Call today or Contact Us to request a barndominium insurance quote.
Our Mission
Our mission is to provide individuals, families, and businesses across the State of Michigan with clear insurance guidance, dependable coverage options, and personal service that helps them make confident decisions about protecting what matters most.
Our Core Values
Relationships Come First
Insurance works best when there is trust. Many of our clients have been with us for years, and some families have worked with our agency for generations. We believe in building long-term relationships, not just selling policies.
Honest Conversations
We believe in straightforward advice. Our job is to explain your options clearly, answer questions honestly, and help you choose coverage that truly fits your situation.
Service You Can Count On
When clients reach out, they deserve real help from real people. Our team works to respond quickly, follow through, and make the insurance process easier whenever possible.
Guidance Over Pressure
Insurance decisions can feel overwhelming. Rather than pushing a quick sale, we focus on helping clients understand their options so they can make confident decisions.
Commitment to Our Community
With offices in Battle Creek and Rochester, we are proud to serve communities across the State of Michigan. Being a local agency means understanding the people and businesses we protect.
The BEW Promise
Real People, Real Help
When you call BEW, a person—not a bot—answers.
Straight Talk
We explain options clearly, without confusion or jargon.
Family First
You’re treated the same as we’d treat family—respect, honesty, and priority.
Follow-Through
Our commitment doesn’t end at sale. We back every policy with accountability and support.
Ready to Work With an Agency That Knows This Part of Texas?
Call us at 806-355-6596, submit a quote request online, or stop by our office at 2921 I-40 W in Amarillo. We'll take a look at what you have, shop it across our carrier network, and come back with honest, straightforward options.