Manufactured Home Insurance for Texas Panhandle Residents
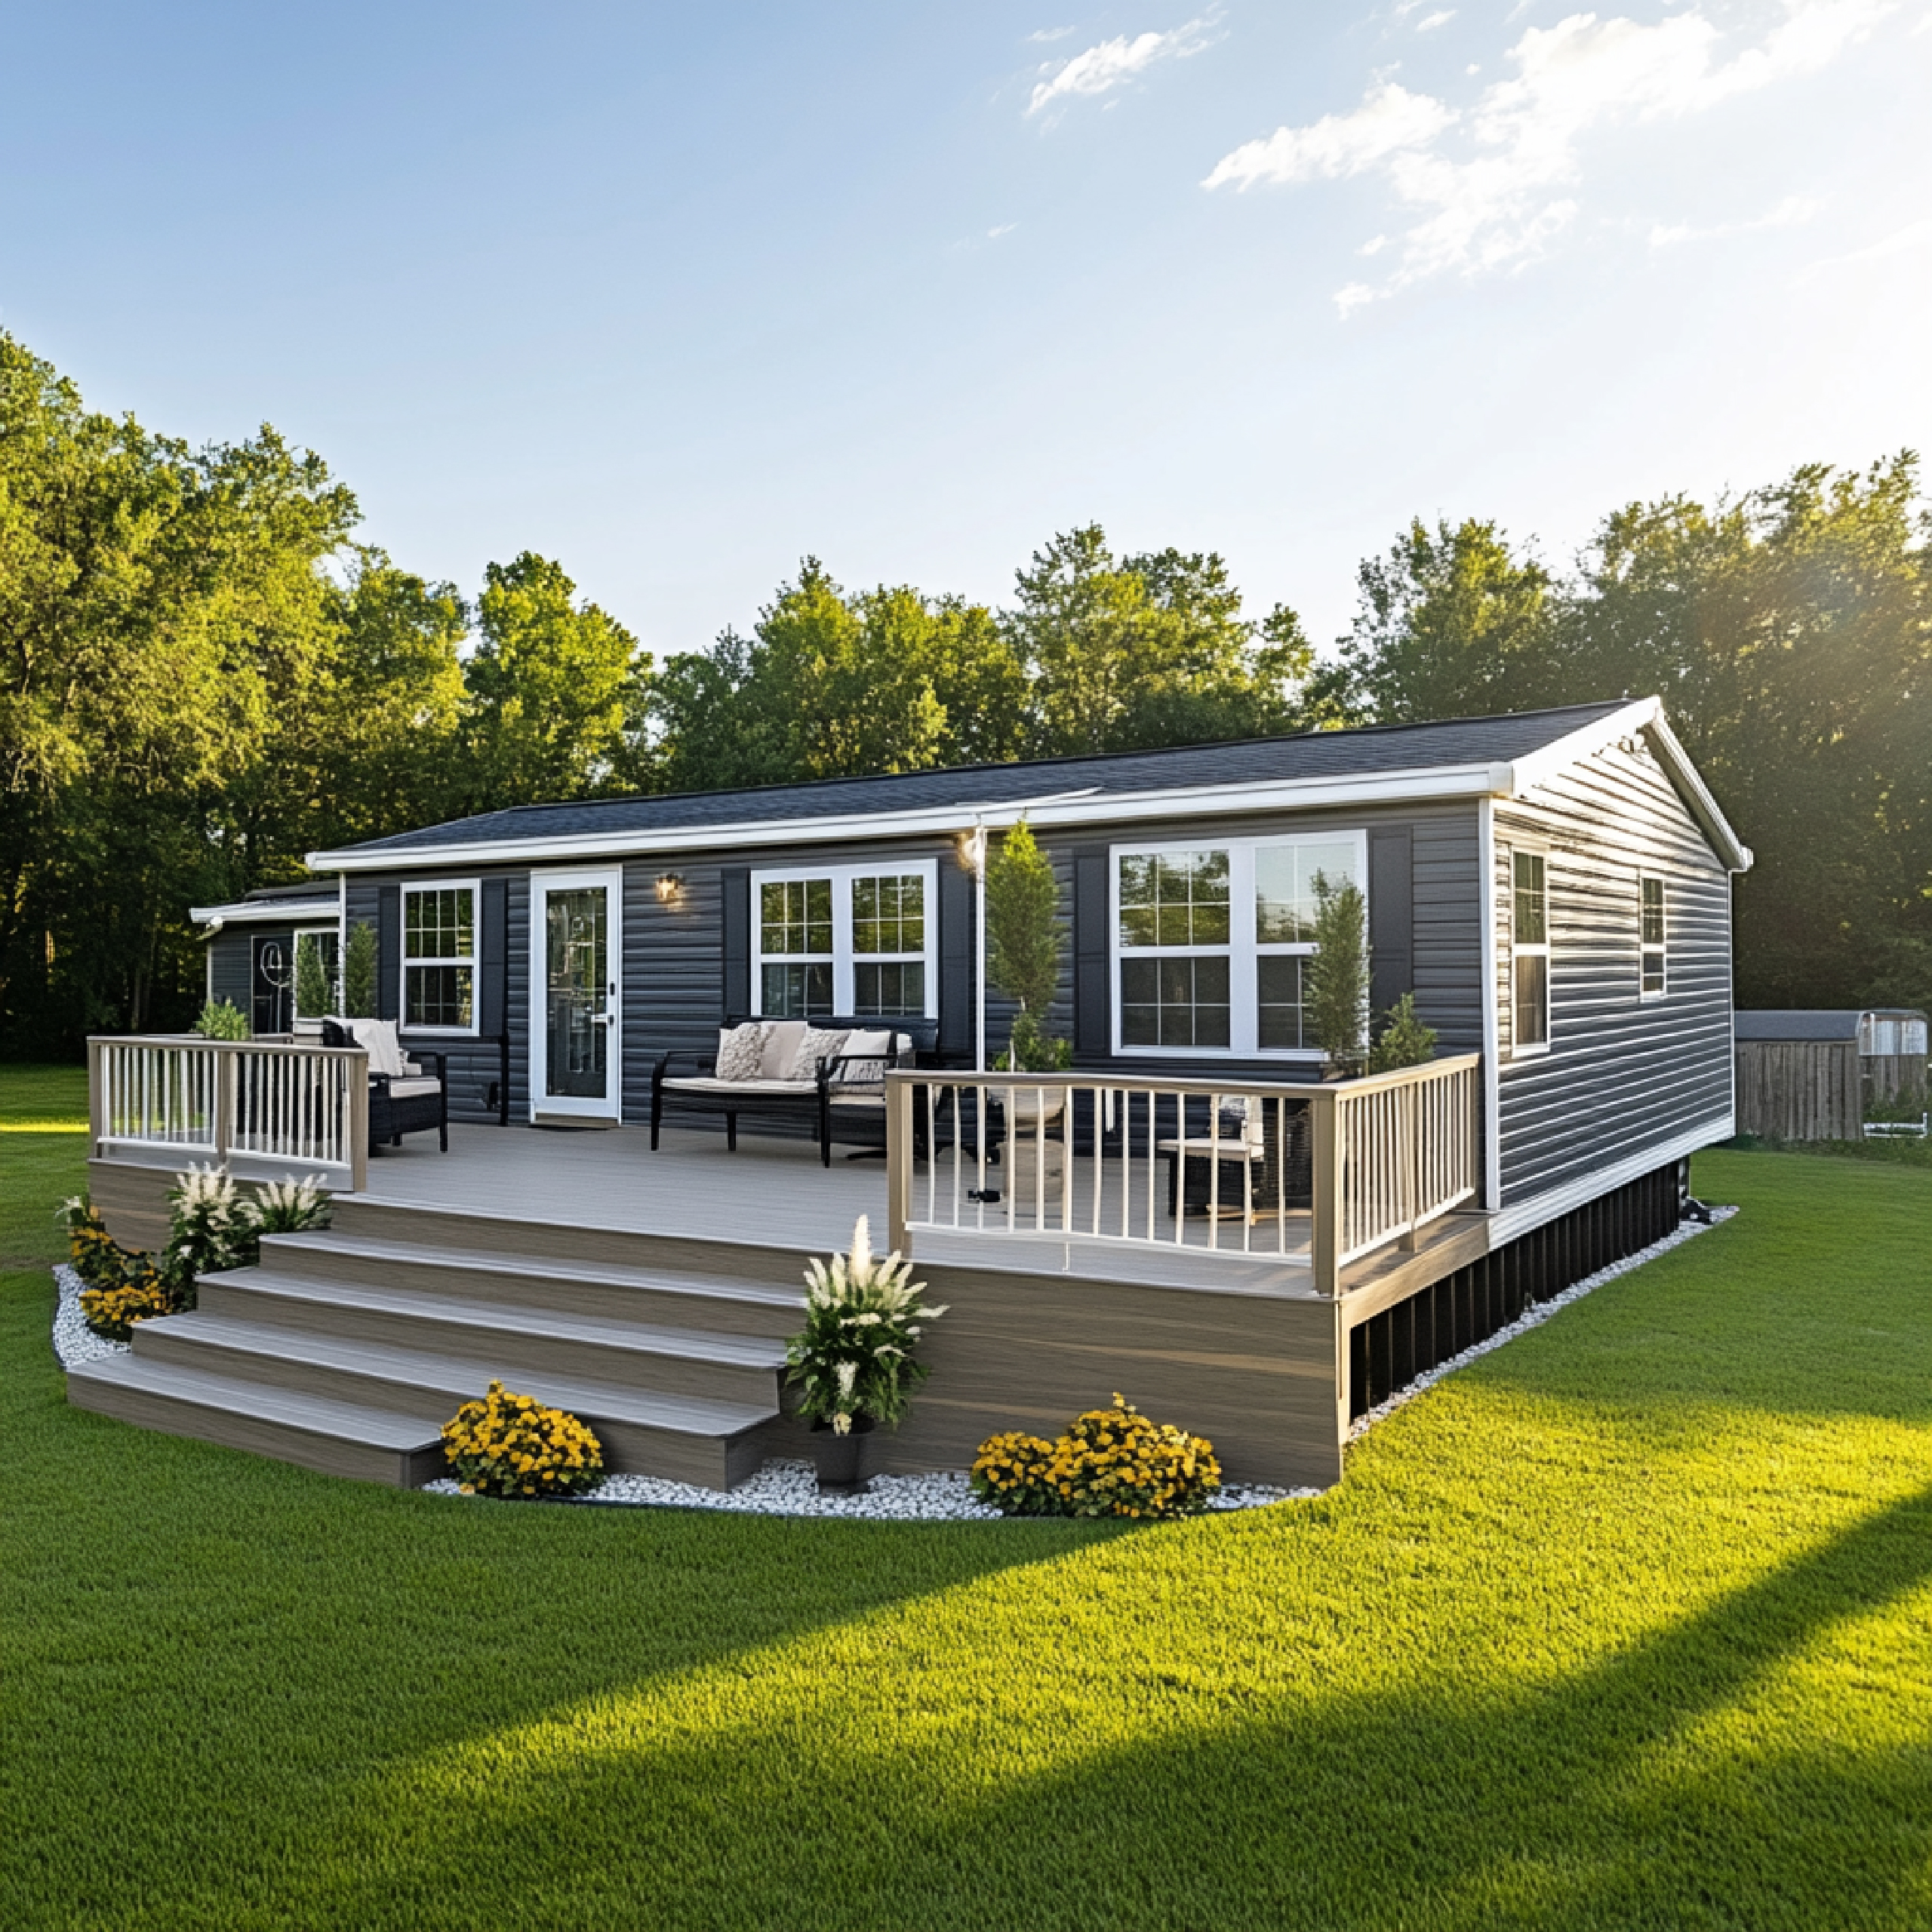
Manufactured homes don't fit a standard homeowners policy — and the wrong coverage can leave you exposed when Texas weather does what Texas weather does. We know exactly what makes manufactured home insurance different, and we've been placing these policies for Panhandle residents for decades.
Coverage Built for the Home You Actually Have
A manufactured home policy covers the specific risks your property faces — it isn't a trimmed-down version of a conventional homeowners form. We'll walk you through each component so you know what you're buying and why it matters.
What Does Life Insurance Cover?
Life insurance is more than a payout—it’s a plan that ensures your family’s future stays on track, even if you’re no longer there to lead it. From mortgage protection to legacy planning, the right policy offers financial security and peace of mind.
Types of Life Insurance We Offer:
Term Life Insurance
Affordable, time-limited protection designed to cover your family during key years—like raising children or paying off your home.
Whole Life Insurance
Lifelong coverage that builds cash value over time. A great option for estate planning, final expense coverage, or long-term savings.
Universal Life Insurance
Flexible protection that combines lifelong coverage with adjustable premiums and a savings component.
Final Expense Insurance
A simple, affordable way to ensure funeral costs and other end-of-life expenses are covered—so your family isn’t left with unexpected bills.
Dwelling Coverage
This is the core of your policy — protection for the physical structure of your manufactured home against covered perils including wind, hail, fire, and more. We'll help you choose between actual cash value and replacement cost coverage, and explain what that difference means when a claim happens.
Liability Coverage
Carports, storage sheds, fencing, and other structures on your property can be covered separately from the main dwelling. If you've built out your lot, we'll make sure what you've added is included.
Liability Coverage
If someone is injured on your property, liability coverage pays for their medical expenses and protects you from legal costs. This applies whether you own your land or lease a lot in a manufactured home community.
Additional Structures
Carports, storage sheds, fencing, and other structures on your property can be covered separately from the main dwelling. If you've built out your lot, we'll make sure what you've added is included.
Personal Property
Your furniture, appliances, electronics, and belongings are covered under the personal property portion of your policy. Coverage limits and conditions vary by carrier — we'll help you match the limit to what you actually own.
Actual Cash Value vs. Replacement Cost — Why It Matters More for Manufactured Homes
This is one of the most important decisions you'll make when setting up a manufactured home policy, and it's one most people don't fully understand until after a claim.
Actual cash value (ACV) pays what your home is worth at the time of a loss — after depreciation. For an older manufactured home, that number can be significantly lower than what it costs to repair or replace it. Replacement cost coverage pays what it actually takes to restore your home to its prior condition, without the depreciation deduction.
Manufactured homes depreciate differently than site-built homes. We'll show you both options with real numbers so you can make an informed decision — not just pick the lower premium.
Carriers Who Specialize in Manufactured Homes
Some carriers won't write manufactured home policies at all. Others will write them but price them poorly or restrict coverage in ways that only show up at claim time. We work with Foremost Insurance — one of the country's leading specialty carriers for non-traditional housing — along with other carriers who have real experience in this space.
That carrier access matters. As an independent agency, we shop your coverage across multiple options and place it with the carrier that fits your home, your lot situation, and your budget. You're not limited to whatever a single-company agent can offer.
What to Know About Older Manufactured Homes and Inspections
Older manufactured homes can present underwriting challenges. Some carriers restrict coverage on homes built before a certain year, and others may require a physical inspection before binding a policy. This isn't unusual — but it can catch people off guard if they're working with an agent who doesn't know the territory.
We've navigated these situations for Panhandle clients for years. If your home is older or has characteristics that might complicate coverage, we'll tell you upfront what to expect and which carriers are the best fit.
Manufactured Home Community Residents — Proof of Insurance Made Simple
Many manufactured home communities in the Amarillo area require proof of insurance before approving residency or renewing a lease. If you're moving into a community or need to satisfy a lender's insurance requirement, we can help you get a policy in place quickly and provide the documentation you need.
We understand how these requirements work and what they typically ask for. Getting covered doesn't have to slow down your move-in timeline.
Do You Need Manufactured Home Insurance in Texas?
Texas doesn't require homeowners or manufactured home insurance by state law. But if you have a mortgage or a land contract on your manufactured home, your lender almost certainly requires it. And if you live in a manufactured home community, your lease agreement may require it as well.
Beyond lender and community requirements, the case for coverage in the Texas Panhandle is straightforward. Hail, wind, and severe storms are real and recurring risks in this region. A policy that fits your home and your exposure gives you a path forward when something goes wrong — without having to absorb the full cost out of pocket.
Frequently Asked Questions About Manufactured Home Insurance in Texas
Can you get insurance on a manufactured home in Texas?
Yes. Manufactured homes are insurable in Texas, and several carriers specialize in this type of coverage. The options available to you depend on factors like the age of your home, its current condition, and where it's located. We work with Foremost and other carriers who write manufactured home policies regularly — including for older homes that some insurers won't touch.Is manufactured home insurance the same as a standard homeowners policy?
No. Manufactured home policies are written on a different form than conventional homeowners policies. The coverage components are similar — dwelling, liability, personal property, additional structures — but the underwriting, depreciation treatment, and carrier options differ. Working with an agent who understands those differences is important.What does manufactured home insurance cover?
A standard manufactured home policy covers the dwelling structure, your personal belongings, liability if someone is injured on your property, and additional structures like carports or storage sheds. Coverage for specific perils — including wind and hail, which are significant risks in the Panhandle — is included based on your policy form. We'll review what's covered and what's excluded before you bind.How does actual cash value vs. replacement cost affect my claim?
Actual cash value pays what your home is worth at the time of the loss, factoring in depreciation. Replacement cost pays what it actually costs to repair or replace your home without that deduction. For manufactured homes — which depreciate differently than site-built homes — this distinction can mean a significant difference in your claim payout. We'll walk you through both options so you can choose with full information. My manufactured home is older. Can I still get coverage? Possibly, yes. Older manufactured homes do face more underwriting scrutiny, and some carriers won't write policies on homes beyond a certain age or condition. An inspection may be required. We've placed coverage for older manufactured homes in the Panhandle before and know which carriers are the right fit for non-standard situations. Call us and we'll give you an honest answer about your options. Do I need insurance if I rent a lot in a manufactured home community? Most manufactured home communities in the Amarillo area require proof of insurance as a condition of residency. Even where it isn't required, your personal belongings, liability exposure, and the structure itself aren't covered by the community's policy. A manufactured home policy covers you — not just the lot.
50 Years of Insuring Texas Homes — Including the Ones That Don't Fit a Standard Form
Herring Agency has been placing insurance for Panhandle residents since 1975. We've insured conventional homes, manufactured homes, barndominiums, ranch properties, and everything in between. If your home doesn't fit a standard form, we know where to take it.
Call us at 806-355-6596 or submit a quote request online. We'll find coverage that fits your home — not just coverage that's easy to write.